Facts
The petitioner challenged the debit/recovery of ₹3,19,164 from his Electronic Cash Ledger on 21 January 2026 towards a tax demand for the period 2018–19.
Source reference: para. 2A tax demand of ₹3,54,630 had been raised by order dated 18 January 2024. The petitioner claimed to have deposited the requisite pre-deposit under Sections 107(6) and 112(8) of the CGST/WBGST Act, 2017, and thereafter preferred an appeal before respondent no. 2. Despite the alleged compliance with the pre-deposit requirements, the authorities recovered the aforesaid amount from the Electronic Cash Ledger. The petitioner submitted a representation dated 2 March 2026 before respondent no. 1 seeking refund or re-credit of the amount recovered.
Source reference: para. 3The petitioner relied on the coordinate Bench decision in M/s. Spandan Electrical v. State of West Bengal & Ors., WPA 28120 of 2025, decided on 17 February 2026.
Source reference: para. 4Issues
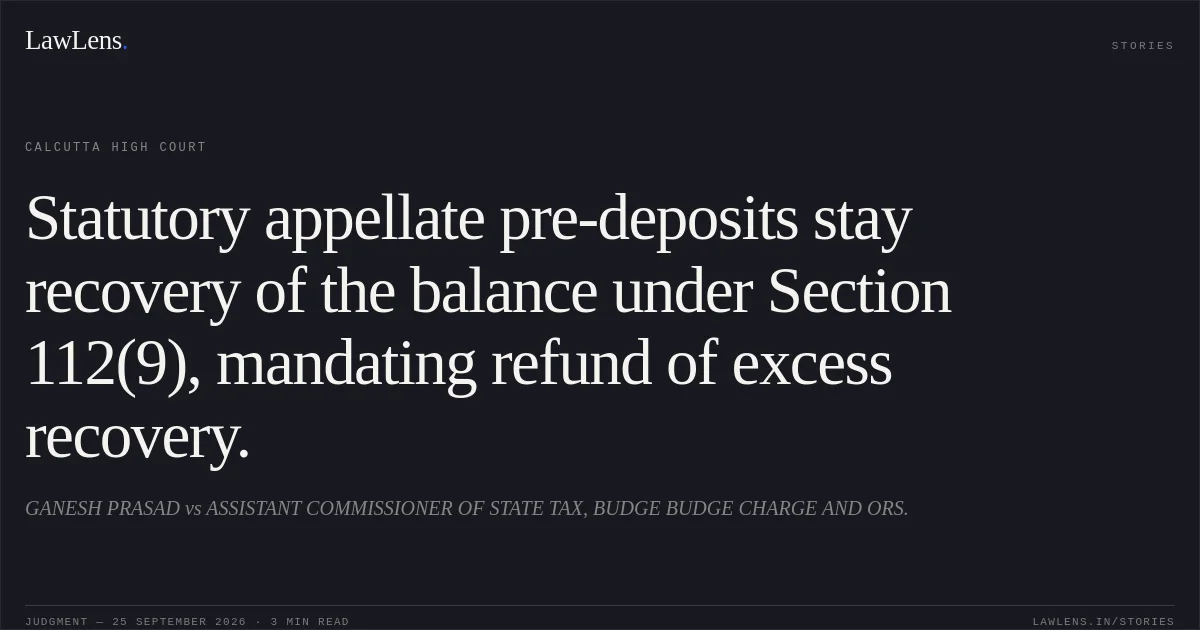
Whether recovery of the balance tax demand from the petitioner’s Electronic Cash Ledger was permissible after payment of the appellate pre-deposits required under Sections 107(6) and 112(8) of the CGST/WBGST Act, 2017.
Source reference: paras. 1–4Whether the petitioner was entitled to consideration of his representation and refund or re-credit of any amount recovered in excess of the cumulative statutory pre-deposits.
Source reference: paras. 4, 7–8Whether the writ petition could be disposed of by directing the competent authority to decide the petitioner’s representation by a reasoned and speaking order, without adjudicating the merits of the tax demand.
Source reference: paras. 7–11Law Applied
The Court applied Sections 107(6), 112(8), and 112(9) of the CGST/WBGST Act, 2017. Sections 107(6) and 112(8) require payment of the prescribed pre-deposits for pursuing appeals at the relevant appellate stages. Under Section 112(9), upon payment of the amount specified under Section 112(8), recovery proceedings for the balance amount are deemed to remain stayed until disposal of the appeal.
Source reference: paras. 4, 6, 8The Court also relied on the coordinate Bench decision in M/s. Spandan Electrical v. State of West Bengal & Ors., which held that any amount recovered beyond the cumulative pre-deposits required under Sections 107(6) and 112(8) must be refunded or re-credited after verification by the GST authorities.
Source reference: para. 4Reasoning
The Court found that the petitioner had established a prima facie case because he asserted that the statutory pre-deposits had been made and that recovery nevertheless took place from his Electronic Cash Ledger.
Source reference: para. 7Since the factual question—whether the required payments under Sections 107(6) and 112(8) had in fact been made—required verification by the tax authorities, the Court did not finally determine the legality of the recovery or the underlying tax demand. Instead, it directed respondent no. 1 to examine the petitioner’s representation in light of Section 112(9), the coordinate Bench precedent, and the relevant payment records. If the authorities found that the recovery exceeded the cumulative pre-deposits, the excess amount was required to be refunded or re-credited.
Source reference: paras. 7–9Holding
The writ petition was disposed of without adjudicating the merits of the tax demand.
Respondent no. 1 was directed to decide the petitioner’s representation dated 2 March 2026 within four weeks from communication of the order, by passing a reasoned and speaking order after granting the petitioner an opportunity of personal hearing. The decision was to be communicated within one week thereafter.
Source reference: para. 7If any amount had been recovered in excess of the cumulative pre-deposits required under Sections 107(6) and 112(8), the authorities were directed to refund or re-credit that amount to the petitioner’s Electronic Cash Credit Ledger in accordance with Section 112(9).
Source reference: para. 8The authority was directed to take an independent decision uninfluenced by the Court’s prima facie observations, and the petitioner was directed not to seek unnecessary adjournments.
Source reference: paras. 9–10Acts & Sections Cited
4 provisions across 2 statutes referred to in this judgment. Each provision opens on LawLens.
Central Goods and Services Tax Act, 20172
West Bengal Goods And Services Tax Act, 20172
Original Court PDF
GANESH PRASADvsASSISTANT COMMISSIONER OF STATE TAX, BUDGE BUDGE CHARGE AND ORS.
Click to open original judgment
Original judgment, available to read, download and summarize on LawLens.in