Facts
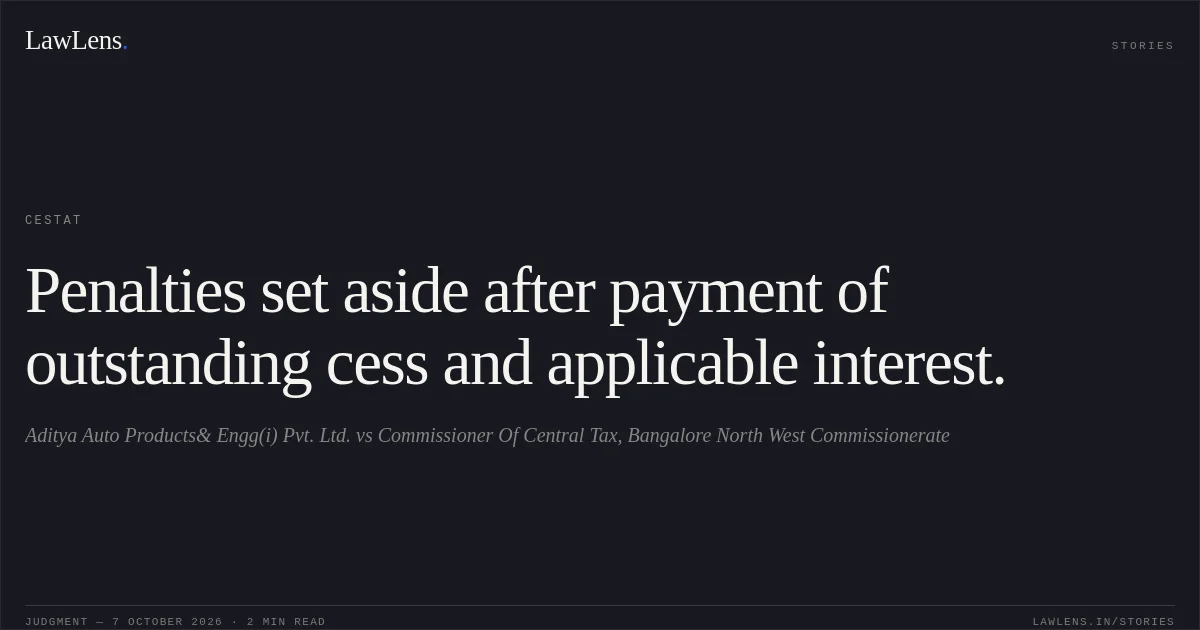
An audit identified alleged short payment of Education Cess and Secondary and Higher Education Cess (SHE Cess), irregular CENVAT credit and short payment of interest.
Source reference: p. 1The adjudicating authority confirmed cess amounts of ₹86,782 and ₹43,426, respectively, with interest and equivalent penalty, and imposed other penalties under the Central Excise Act, 1944.
Source reference: p. 1The Commissioner (Appeals) upheld the order, leading to this appeal.
Source reference: p. 1The appellant stated that it had paid the cess and applicable interest, and relied, among other matters, on a prior Tribunal decision in its own case concerning Rule 8(3A) of the Central Excise Rules, 2002.
Source reference: pp. 2–5The Revenue disputed the appellant’s position on the interest shortfall and penalties and submitted that the cess payments had not been appropriated in the original order.
Source reference: pp. 5–6Issues
1. Whether the amounts paid by the appellant towards the confirmed cess liabilities and applicable interest should be appropriated against the demands.
Source reference: pp. 5–62. Whether the penalties imposed for the alleged short payments, including the penalty linked to Rule 8(3A), were sustainable in the circumstances.
Source reference: pp. 1, 5–6Law Applied
Rule 8(3A) of the Central Excise Rules, 2002, which concerned payment of duty during default, was held unconstitutional by the Gujarat High Court in Indsur Global Ltd. v. Union of India, 2014 (310) E.L.T. 833 (Guj.), and that ruling was followed by the Madras High Court in Malladi Drugs & Pharmaceuticals Ltd. v. Union of India, 2015 (323) E.L.T. 489 (Mad.), and A.R. Metallurgicals P. Ltd., 2015 (322) E.L.T. 49 (Mad.).
Source reference: p. 5The Tribunal also referred to its earlier decision in the appellant’s own case, which applied those authorities and set aside a demand raised under Rule 8(3A).
Source reference: p. 5The respondent relied on the proviso to Rule 3(4) of the CENVAT Credit Rules, 2004, concerning the extent of credit available for payment of duty for a particular month or quarter, and on Rule 8(3) of the Central Excise Rules, 2002, in support of the interest and penalty demands.
Source reference: p. 5Reasoning
The Tribunal noted that the appellant had paid the amounts with applicable interest and had also paid the balance interest during the proceedings.
Source reference: pp. 4–6It considered the earlier decision in the appellant’s own case, which had set aside a demand under Rule 8(3A) in light of the cited High Court rulings.
Source reference: p. 5On the evidence and the circumstances of the case, the Tribunal upheld appropriation of the amounts paid and set aside the penalties; it did not separately elaborate on the respondent’s Rule 3(4) argument.
Source reference: p. 6Holding
The Tribunal held that the amounts paid by the appellant with applicable interest should be appropriated and that the penalties were to be set aside.
The appeal was partly allowed.
Source reference: p. 6Acts & Sections Cited
4 provisions across 2 statutes referred to in this judgment. Each provision opens on LawLens.
Central Excise Act, 19442
Central Goods and Services Tax Act, 20172
Original Court PDF
Aditya Auto Products& Engg(i) Pvt. Ltd.vsCommissioner Of Central Tax, Bangalore North West Commissionerate
Click to open original judgment
Original judgment, available to read, download and summarize on LawLens.in