Facts
Gajendra Dadsena, a government teacher, died in a road accident on 18 January 2020.
Source reference: para. 1–2, 6His major son, Deepak Kumar Dandsena, sought compensation under Section 166 of the Motor Vehicles Act, 1988.
Source reference: para. 1–2, 6The Motor Accident Claims Tribunal awarded Rs. 36,09,676, calculating the deceased’s monthly income at Rs. 47,943, adding 15% for future prospects, applying a multiplier of 11, and deducting one-half for personal expenses.
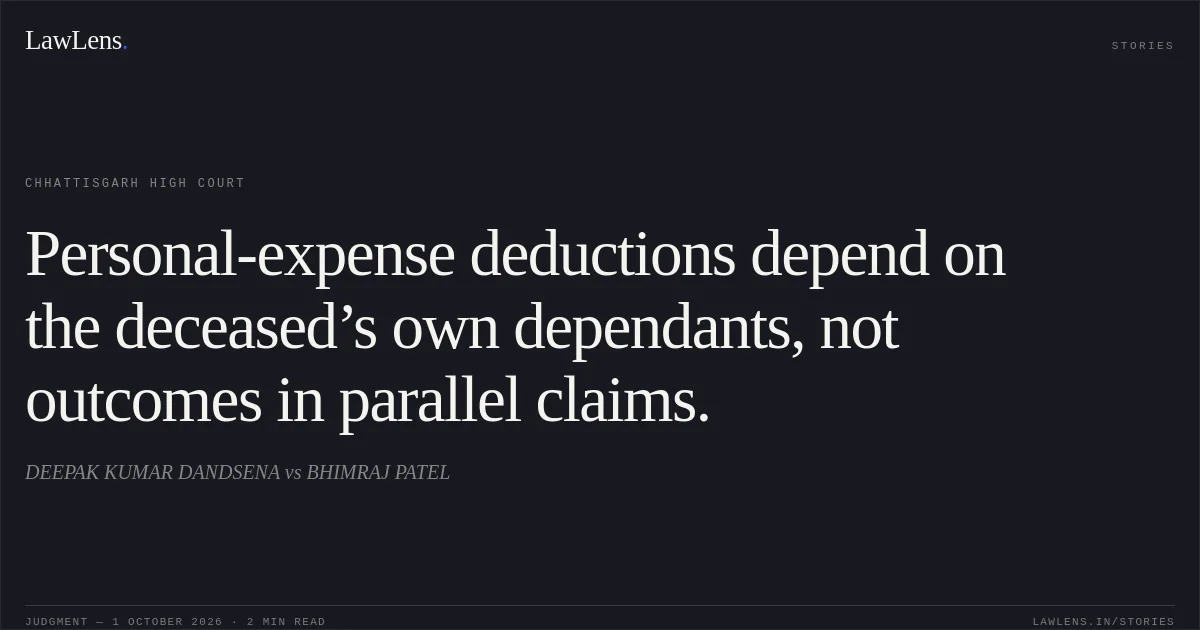
Source reference: para. 1–2, 6On appeal under Section 173, the claimant challenged only the one-half deduction, arguing that one-third had been deducted in a separate claim arising from the same accident for his mother’s death.
Source reference: para. 3, 7Issues
1. Whether the Tribunal erred in deducting one-half, rather than one-third, of the deceased’s income towards personal and living expenses when computing compensation.
Source reference: para. 3, 7–82. Whether the deduction applied in the separate claim concerning the deceased’s wife required the same deduction to be applied in this claim.
Source reference: para. 3, 7–8Law Applied
Section 166 of the Motor Vehicles Act, 1988 provides for a claim for compensation arising from a motor-vehicle accident, while Section 173 provides for an appeal against an award of the Claims Tribunal.
Source reference: para. 1–2Under Sarla Verma v. Delhi Transport Corporation, (2009) 6 SCC 121, and National Insurance Co. Ltd. v. Pranay Sethi, (2017) 16 SCC 680, the deduction towards a deceased’s personal and living expenses is assessed by reference to the financial dependants left by that particular deceased; the deduction in a separate claim does not determine the deduction in another claim.
Source reference: para. 8Reasoning
The Court accepted the Tribunal’s assessment of the deceased’s salary, future prospects, and multiplier.
Source reference: para. 6It held that the one-third deduction made in the separate claim for the mother’s death did not automatically govern the father’s claim.
Source reference: para. 7–9Applying Sarla Verma and Pranay Sethi, the Court treated the deduction as specific to the dependants of the individual whose death was the subject of the claim.
Source reference: para. 7–9It found the Tribunal’s one-half deduction neither unreasonable nor unsustainable and rejected the claimant’s limited ground of appeal.
Source reference: para. 7–9Holding
The Court answered the challenged-deduction issues against the appellant, holding that the one-half deduction was properly applied and that the deduction in the separate claim did not require a one-third deduction here.
The appeal was dismissed, and the Tribunal’s award was not enhanced.
Source reference: para. 9Acts & Sections Cited
2 provisions across 1 statute referred to in this judgment. Each provision opens on LawLens.
Motor Vehicles Act, 19882
Original Court PDF
DEEPAK KUMAR DANDSENAvsBHIMRAJ PATEL
Click to open original judgment
Original judgment, available to read, download and summarize on LawLens.in